
- Sony Group recently introduced two compact G Master super telephoto primes, the FE 400mm f/4.5 and FE 600mm f/6.3, targeting high performance outdoor and wildlife imaging with lighter builds and advanced autofocus and stabilization features.
- The new lenses add a middle tier in Sony Group’s super telephoto lineup, giving professionals and serious hobbyists lighter, more accessible tools that can still pair with high resolution bodies for flexible cropping and field use.
- This article examines how Sony Group’s broader investment narrative is shaped by these compact G Master lenses in the imaging segment.
Spot fresh potential alongside Sony Group by scanning a curated set of 74 high quality undiscovered gems that is built around strong fundamentals and under-the-radar growth stories in adjacent sectors.
Advertisement
Sony Group Investment Narrative Recap
To own Sony Group, you generally need to believe the shift toward content, services, sensors and creator hardware can offset pressure in legacy electronics and cyclical hardware. The compact G Master super telephotos fit that creation centric push, but by themselves they are unlikely to move group earnings near term, particularly with quarterly revenue expected to soften.
The more immediate swing factors still sit in PlayStation engagement, content monetization and the Imaging & Sensing Solutions pipeline, while geopolitical and supply chain costs remain key risks. The new lenses help defend Sony Group’s imaging positioning, yet do not materially change those broader catalysts or the operational risk profile investors are already weighing.
The launch of the FE 400mm f/4.5 and FE 600mm f/6.3 G Master primes is the clearest link between this news and Sony Group’s existing catalysts. These lenses lean into higher value creator gear, which aligns with the push toward creation centric devices and sensor based ecosystems that support more durable, higher margin revenue over time.
On the flip side, this type of product expansion keeps Sony Group exposed to competition in imaging and to hardware related supply chain pressures that analysts already flag as risk factors. Execution now rests on keeping these premium tools tightly tied to Sony bodies, services and sensor leadership, so that each lens sale supports the broader earnings mix investors are watching.
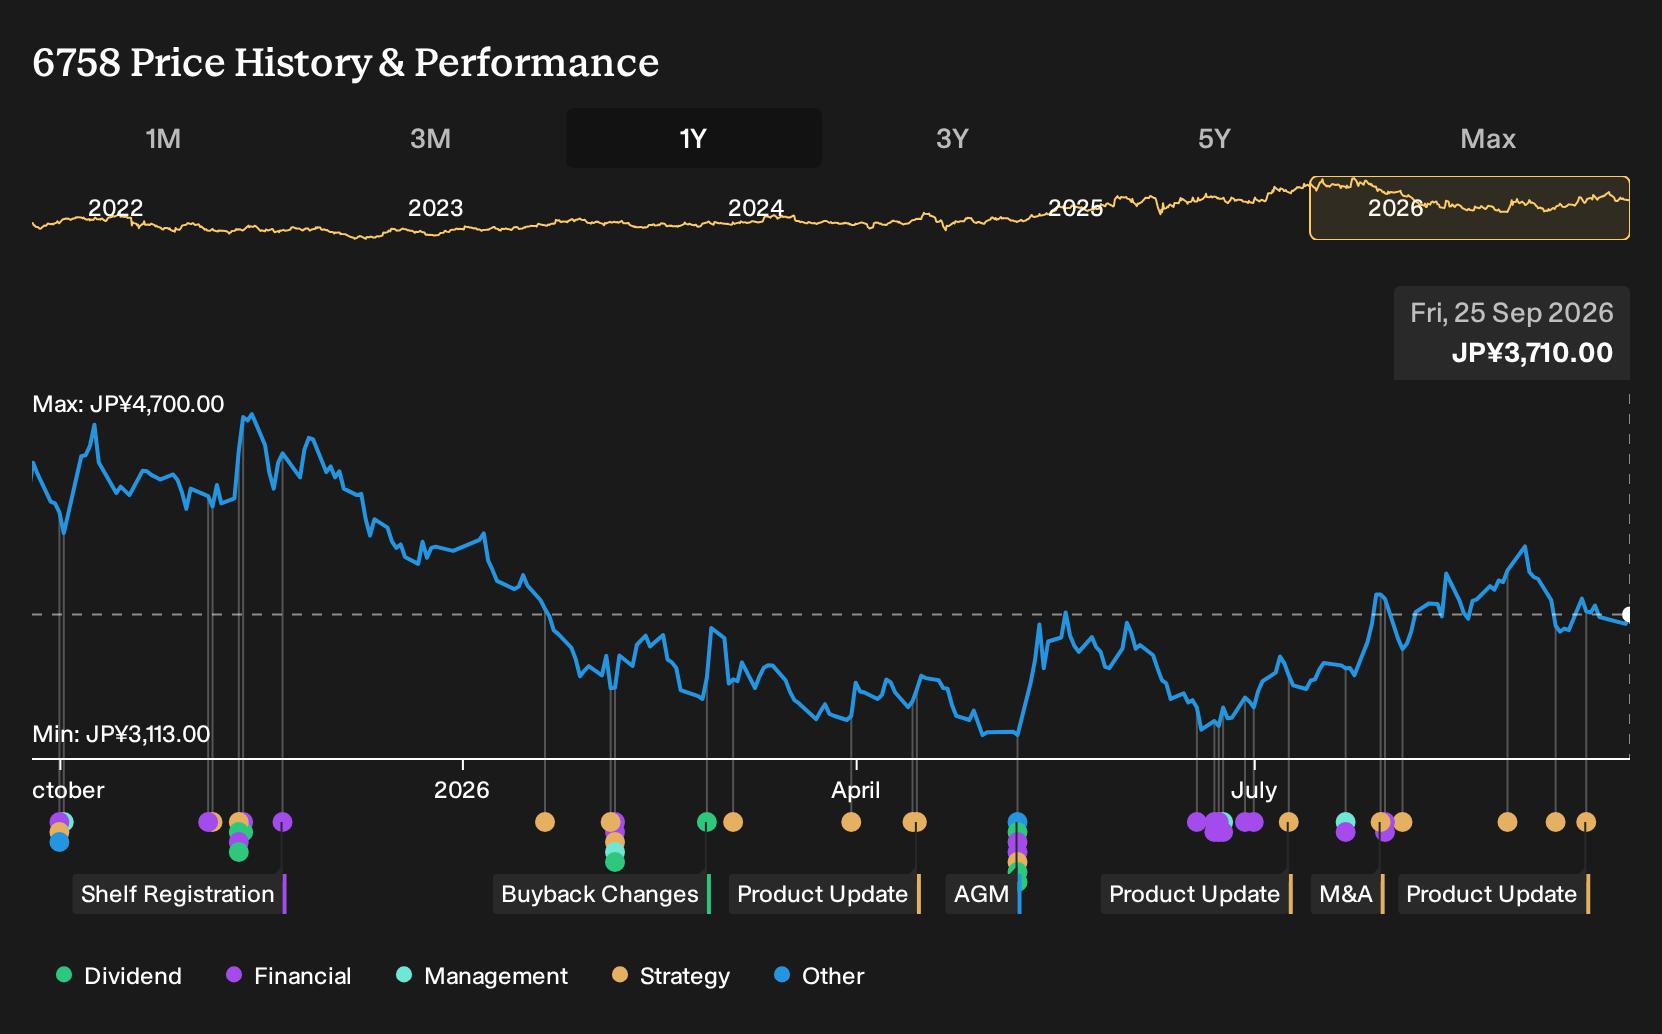
Sony Group’s current analyst narrative points to revenue of ¥13,819.9b and earnings of ¥1,439.0b by 2029, based on forecast yearly top line growth of 2.9% and an earnings increase of roughly ¥325.0b from ¥1,114.0b today.
Uncover why Sony Group’s fair value indicates a 31% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on gaming risk rather than imaging upside. The most bearish analysts saw Sony Group revenue easing toward ¥12,209.9b by 2029 with earnings only around ¥1,118.9b, which is far below the consensus path. Those forecasts were set before these compact G Master launches, so opinions may shift.
Explore 2 other Sony Group fair value estimates, including one that suggests it could be worth just ¥4,848!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sony Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sony Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sony Group’s overall financial health at a glance.
Looking for more investment ideas beyond Sony Group?
If the Sony Group story has you thinking about where else quality, durability and sensible pricing power might show up, the Simply Wall St Screener can help you cast a wider net without losing focus on fundamentals.
- If you prefer strong balance sheets and resilient business models over excitement and hype, then start with a list of solid balance sheet and fundamentals (22 results) that filters for financial strength and staying power.
- If capital preservation and steadier return profiles matter most to you, review a 21 resilient stocks with low risk scores that concentrates on businesses with lower assessed risk scores.
- If you want exposure to companies that still fly under most radars, yet have fundamentals you can actually underwrite, then scan a 74 high quality undiscovered gems and see what else might deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
New:Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks
Have feedback on this article? Concerned about the content? Get in touch with us directly.Alternatively, email editorial-team@simplywallst.com
The old reason to buy emerging markets was their young, growing populations. Most of them aren’t young anymore.
I was never a fan of emerging markets investing tbh. Good companies are everywhere.
The best EM bet might be the AI companies. Most emerging markets will consume this rather than build the frontier layer, and consuming it is where the real economic gain is. Leapfrogging to AI-delivered services without the legacy infrastructure is a bigger jump than upgrading existing systems. The benefit accrues locally, the earnings accrue to the supplier.
Where to invest when populations stop growing

Artificial intelligence can do a lot for production. But consumption is a different issue, and changing demographics aren’t helping. So where do you invest when populations aren’t growing?
10
Sep 24, 2026
About TSE:6758
Sony Group
Develops, designs, produces, manufactures, supplies, and sells electronic equipment, instruments, and devices for consumer, professional, and industrial use in Japan, the United States, Europe, China, the Asia-Pacific, and internationally.
Flawless balance sheet and undervalued.
Similar Companies
-
Panasonic Holdings
-
Casio ComputerLtd
Market Insights
Where to invest when populations stop growingAL
Alegget
What happens to energy stocks as the fix gets built?MI
mitchell_lawler
Are social media stocks the new Big Tobacco?AL
Alegget
Advertisement
Weekly Picks

Ceazaron Buffalo Potash·5 days ago
Under the radar: This $78M stock controls a $1.5B project and it’ll start producing in a few months
Fair Value:CA$1.0613.2% undervalued
40followersusers have followed this narrative
·0commentsusers have commented on this narrative
·10likesusers have liked this narrative
TO

Tokyoon Novo Nordisk·about 2 months ago
EU#2 – From Humble Beginnings to Global Powerhouse
Fair Value:DKK 851.0470.3% undervalued
83followersusers have followed this narrative
·19commentsusers have commented on this narrative
·27likesusers have liked this narrative
HA

HarishPKon Zoetis·28 days ago
Decision Making Under Ambiguity – A Case Study on Expectations Investing
Fair Value:US$91.322.2% undervalued
13followersusers have followed this narrative
·1commentusers have commented on this narrative
·6likesusers have liked this narrative
RE

RedCandleRxon AppLovin·11 days ago
Why the Market Still Misprices AppLovin as Just a Gaming Network
Fair Value:US$50738.7% undervalued
19followersusers have followed this narrative
·1commentusers have commented on this narrative
·8likesusers have liked this narrative
RecentlyUpdated Narratives

ANTONI0on SEEK·about 2 hours ago
SEEK Limited (ASX: SEK). A 63% Drawdown, and the One Question That Decides It
Fair Value:AU$10.455.9% overvalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
ES

Estebanon Copart·about 7 hours ago
CPRT 04-2026
Fair Value:US$18.9745.4% overvalued
3followersusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
J_

J_Tyraderon Sezzle·about 11 hours ago
Sezzle: Trading 41% below what it’s worth
Fair Value:US$187.8840.7% undervalued
1followerusers have followed this narrative
·0commentsusers have commented on this narrative
·0likesusers have liked this narrative
Popular Narratives

AnalystConsensusTargeton NVIDIA·about 2 months ago
NVDA: Expanding AI Demand Will Drive Major Data Center Investments Through 2026
Fair Value:US$302.8325.7% undervalued
1512followersusers have followed this narrative
·8commentsusers have commented on this narrative
·35likesusers have liked this narrative
AN

AnalystConsensusTargeton Alphabet·2 days ago
AI Demand Must Outrun Infrastructure Buildout
Fair Value:US$429.4619.9% undervalued
1664followersusers have followed this narrative
·0commentsusers have commented on this narrative
·19likesusers have liked this narrative
AN

AnalystConsensusTargeton Amazon.com·about 1 month ago
AMZN: Acceleration In Cloud And AI Will Drive Margin Expansion Ahead
Fair Value:US$32723.6% undervalued
1681followersusers have followed this narrative
·1commentusers have commented on this narrative
·16likesusers have liked this narrative
